Our content is for education only and is not personal financial advice. Some links may earn us a commission at no cost to you, which never affects our recommendations.
Key takeaways
- Budgeting weekly helps manage cash flow.
- Prioritize essential expenses in your plan.
- Adjust your budget as needed for flexibility.
Budgeting is a fundamental skill in personal finance that helps you manage your money effectively. When you get paid weekly, it offers unique opportunities and challenges that can influence your budgeting strategy. Weekly paychecks can help you align your income with your expenses more closely, allowing for better cash flow management. However, it can also complicate your budgeting process if not handled correctly.
This guide will explore how to budget when you get paid weekly, offering practical steps and strategies to ensure your financial health. You will learn how to structure your budget, prioritize your expenses, and make adjustments as needed. With the right approach, you can turn your weekly pay into a powerful tool for achieving your financial goals.
Whether you are a seasoned budgeter or just starting, understanding how to manage your finances on a weekly basis can lead to improved stability and peace of mind. Let’s dive into the details of setting up an effective weekly budget.
Understanding Weekly Budgeting
Weekly budgeting involves creating a spending plan based on your income, which is received every week. This method can be particularly useful for those who work hourly jobs or have irregular income streams. By budgeting weekly, you can better track your spending and make necessary adjustments promptly. Here are some key elements to understand about weekly budgeting:
- Income Tracking: Begin by determining your total weekly income. This includes your salary or wages, any side hustles, and any additional sources of income.
- Expense Identification: List all your regular expenses, such as rent, utilities, groceries, and transportation. Be sure to include any irregular expenses that may arise.
- Time Frame: Since your income is weekly, consider dividing your expenses into weekly segments. This allows you to see how much you can allocate each week effectively.
Setting Up Your Weekly Budget
To set up your weekly budget, follow these steps:
1. Gather Financial Information
Start by collecting all relevant financial documents, including pay stubs, bills, and bank statements. This information will provide a clear picture of your income and expenses. Understanding your financial situation is crucial for creating an effective budget.
2. List Your Income
Next, write down your total weekly income. If you have multiple income sources, sum them up for a comprehensive view. For example:
| Income Source | Amount |
|---|---|
| Job Salary | $600 |
| Side Hustle | $150 |
| Freelance Work | $100 |
| Total Income | $850 |
3. Identify Fixed and Variable Expenses
Break down your expenses into fixed and variable categories. Fixed expenses are those that remain constant each month, such as rent or mortgage payments, while variable expenses can change, like groceries or entertainment. Understanding this distinction helps in planning your budget more effectively.
- Fixed Expenses: Rent, utilities, insurance, subscriptions
- Variable Expenses: Groceries, dining out, transportation, entertainment
Allocating Your Income
Once you have a clear picture of your income and expenses, it’s time to allocate your income effectively. This step is crucial for ensuring you can cover your expenses while also saving or paying off debt.
1. Use the 50/30/20 Rule
One popular budgeting strategy is the 50/30/20 rule. This method suggests allocating:
- 50% of your income to needs (essential expenses)
- 30% to wants (non-essential expenses)
- 20% to savings and debt repayment
For example, if your weekly income is $850, your allocations would look like this:
- Needs: $425
- Wants: $255
- Savings/Debt: $170
2. Prioritize Essential Expenses
Ensure that your essential expenses are covered before allocating money to discretionary spending. This includes rent, utilities, groceries, and transportation costs. Make a list of these essential expenses and ensure they fit within your allocated budget.
3. Adjust for Irregular Expenses
Irregular expenses can throw off your budget if not accounted for. Consider setting up a sinking fund for these expenses, which allows you to save a little each week for future costs, such as car repairs or medical bills. For more information on sinking funds, check out Understanding Sinking Funds.
Tracking Your Spending
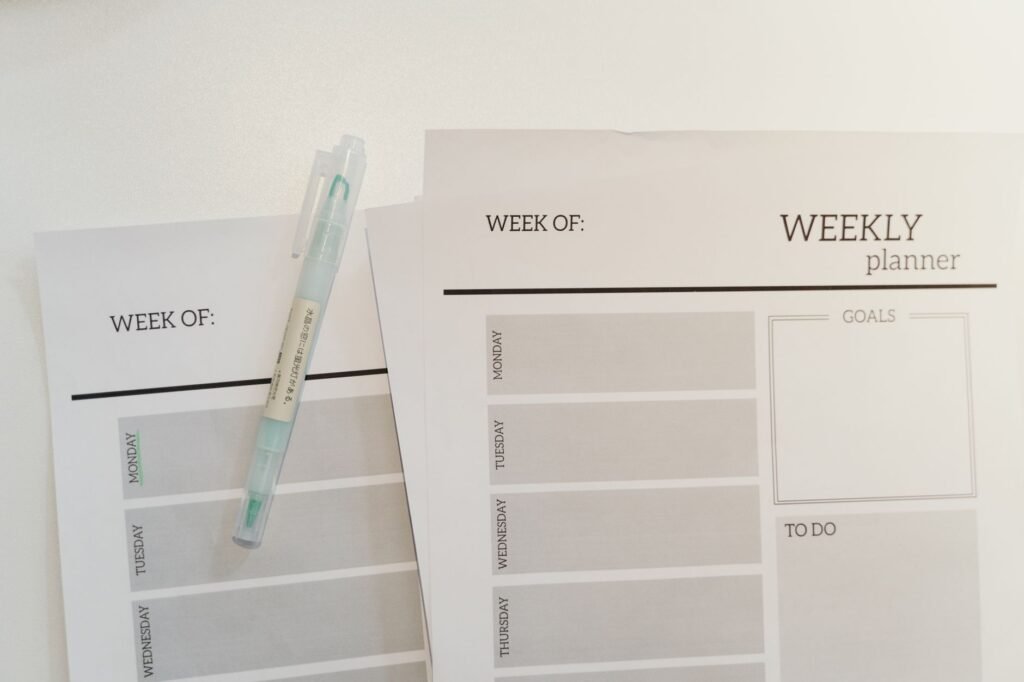
Tracking your spending is a vital part of maintaining your weekly budget. Without monitoring, it’s easy to overspend and lose sight of your financial goals.
1. Use Budgeting Tools
Consider using budgeting apps or software that can help you track your spending in real time. Many apps can connect to your bank accounts, providing an overview of your finances at a glance.
2. Review Weekly
Set aside time each week to review your spending. Compare your actual expenses against your budget. This practice helps identify areas where you may need to adjust your budget or spending habits.
3. Adjust Your Budget as Needed
Life is unpredictable, and your budget may need to change. If you find you consistently overspend in certain categories, consider adjusting your budget to reflect your actual spending patterns.
Saving and Preparing for Future Expenses
Saving is a crucial aspect of any budget. With weekly paychecks, you can build savings progressively, making it easier to reach your financial goals.
1. Establish an Emergency Fund
Having an emergency fund is essential for financial security. Aim to save three to six months’ worth of living expenses. Start small, saving a portion of your weekly pay until you reach your goal.
2. Save for Specific Goals
Consider setting up separate savings accounts for different goals, such as vacations, home improvements, or large purchases. This will help you stay organized and motivated to save.
3. Automate Savings
Automating your savings can make the process easier. Set up automatic transfers from your checking account to your savings account each week. This way, you prioritize saving before spending your paycheck.
Incorporating Irregular Expenses into Your Weekly Budget
Identifying Irregular Expenses
Irregular expenses are costs that do not occur on a regular basis, making them easy to overlook in a weekly budget. Examples include annual subscriptions, car maintenance, or holiday gifts. To effectively incorporate these into your budgeting strategy, start by listing all potential irregular expenses you might incur throughout the year. This will help you understand the scope of these costs and plan accordingly.
Consider creating a dedicated section in your budget for irregular expenses. You can estimate the total for each type of expense based on past spending and divide that total by the number of weeks in the year. This will give you a clearer picture of how much to set aside each week. Here’s a simple list to help identify common irregular expenses:
- Insurance premiums
- Property taxes
- Annual subscriptions (e.g., streaming services, software)
- Gifts and celebrations (e.g., birthdays, holidays)
- Seasonal expenses (e.g., vacations, back-to-school shopping)
Creating a Buffer for Unexpected Costs
No matter how carefully you budget, unexpected expenses can still arise. Setting aside a buffer can help you manage these costs without derailing your financial plan. A good rule of thumb is to allocate a small percentage of your weekly income for unforeseen expenses. This allows you to maintain financial flexibility while staying on track with your budgeting goals.
As you build your buffer, consider what types of unexpected expenses are most likely to occur. For example, if you have an older vehicle, you might want to set aside more funds for potential repairs. Being proactive in your budgeting can ultimately save you from financial stress. Here’s how to establish an effective buffer system:
- Assess your past spending on unexpected items.
- Determine a reasonable percentage of your income to save weekly.
- Keep the buffer in a separate savings account for easy access.

Utilizing Digital Tools for Budget Management
Choosing the Right Budgeting Apps
In today’s digital age, there are numerous budgeting apps available that can simplify your financial management. These tools often come with features that allow you to track your spending, set savings goals, and receive alerts when you approach your budget limits. When selecting a budgeting app, consider factors such as user-friendliness, compatibility with your devices, and the specific features you need.
Popular budgeting apps include Mint, YNAB (You Need A Budget), and EveryDollar. Each app has its unique strengths, so take the time to explore them and choose one that aligns with your financial habits and goals. Here are key features to look for:
- Automatic transaction tracking
- Customizable budget categories
- Goal-setting capabilities
- Secure data encryption
- Integration with bank accounts and credit cards
Leveraging Online Banking Features
Many banks and credit unions offer online banking features that can enhance your budgeting efforts. For instance, you can set up alerts for low balances, categorize transactions, and analyze your spending patterns. Additionally, some banks allow you to create savings goals or sub-accounts to help you allocate funds effectively.
Take advantage of these features to streamline your budgeting process. Regularly checking your online banking dashboard can provide insights into your spending habits and help you adjust your budget as needed. Here’s how to maximize online banking tools:
- Enable transaction notifications to stay informed.
- Utilize spending analysis tools to track where your money goes.
- Set up automatic transfers to savings or investment accounts.
Engaging the Family in Budgeting
Creating a Family Budgeting Plan
When managing finances as a household, it’s essential to involve all family members in the budgeting process. Creating a family budgeting plan fosters a sense of shared responsibility and helps everyone understand the importance of financial discipline. Schedule regular family meetings to discuss your budget, review spending, and set financial goals together.
During these meetings, encourage open dialogue about money. Discuss the reasons behind certain budgetary decisions and allow family members to express their opinions and concerns. This approach can lead to better cooperation and adherence to the budget. Here are steps to create an effective family budgeting plan:
- Gather input from all family members about their financial needs and goals.
- Establish joint financial goals, such as saving for a vacation or paying off debt.
- Assign specific budgeting responsibilities to each member.
Teaching Financial Literacy to Children
Incorporating financial literacy into your family’s budgeting discussions is crucial for teaching children about money management. Start by introducing simple concepts like saving, spending wisely, and the importance of budgeting. You can use real-life scenarios to illustrate these points, such as involving children in planning a family outing or saving for a toy they want.
Consider using tools and games that promote financial education. Many online platforms offer engaging activities designed for kids to learn about money management in a fun way. Here are some effective methods to teach children about budgeting:
- Use a savings jar to visually represent saving goals.
- Encourage them to earn money through chores or small tasks.
- Discuss the value of comparing prices when shopping.
Building an Emergency Fund
Why You Need an Emergency Fund
An emergency fund acts as a financial safety net, providing you with peace of mind in times of unforeseen expenses. Such expenses may include medical bills, car repairs, or sudden job loss. Without an emergency fund, you may find yourself resorting to high-interest credit cards or loans, which can lead to financial distress.
How to Establish Your Emergency Fund
When establishing an emergency fund, it is essential to aim for three to six months’ worth of living expenses. Start by determining your monthly expenses and then multiply that figure accordingly. To build this fund on a weekly paycheck, consider setting aside a small percentage of each paycheck until you reach your goal.
- Calculate your total monthly expenses.
- Divide that number by 4 to get a rough weekly target.
- Make it a non-negotiable line item in your budget.
Incorporating Savings Goals into Your Weekly Budget
Identifying Your Savings Goals
Your financial aspirations can range from short-term goals like vacations to long-term ones such as retirement. Identifying these goals is crucial as it helps in shaping your budgeting strategy. Once you know what you are saving for, you can allocate funds accordingly within your weekly budget.
Creating a Savings Plan
To effectively save for your goals, create a separate line item in your weekly budget for each goal. Determine how much you need to save weekly to reach your targets within your desired time frame. Breaking down larger savings goals into manageable weekly contributions can make the process less daunting.
- Write down your savings goals.
- Determine the total amount needed for each goal.
- Calculate how much to save weekly to meet each goal.
Reviewing and Adjusting Your Budget Regularly
The Importance of Regular Reviews
Reviewing your budget regularly is essential to ensure that it remains aligned with your financial goals and changing circumstances. As your income, expenses, and financial priorities shift, your budget should be flexible enough to accommodate these changes. Frequent reviews help in identifying areas where you may be overspending or where you can cut back.
How to Conduct a Budget Review
Set aside time weekly or monthly to review your budget. During this review, assess your spending against your budgeted amounts. Make adjustments as necessary to reflect any changes in income or expenses. This proactive approach can prevent financial stress and ensure that you stay on track with your goals.
- Schedule a regular time for your budget review.
- Compare actual spending to your budgeted amounts.
- Adjust your budget for any life changes or new financial goals.
Be mindful of common budgeting mistakes that can derail your financial plans.
- Failing to account for irregular expenses can lead to overspending.
- Neglecting to track your spending may result in exceeding your budget.
- Not adjusting your budget for life changes can cause financial strain.
- Relying solely on a budgeting app without regular manual checks can overlook errors.
Frequently Asked Questions
How do I handle irregular income when budgeting weekly?
For those with irregular income, consider averaging your income over a few months to determine a baseline amount. Use this figure to create a flexible budget that adjusts based on actual earnings.
Can I use the same budget for monthly expenses?
Yes, you can adapt your weekly budget to accommodate monthly expenses by breaking them down into weekly amounts. For example, if you have a $1,200 rent payment due monthly, allocate $300 each week.
What if I overspend one week?
If you overspend, analyze where the extra costs came from and adjust your budget or spending in the following weeks to compensate. Consider cutting back on non-essential expenses temporarily.
How can I stay motivated to stick to my budget?
Set specific financial goals and celebrate small victories along the way. Tracking your progress and seeing how your budget helps you achieve your goals can also motivate you to stay on track.
The Bottom Line
Budgeting when you get paid weekly can be an effective way to manage your finances, control spending, and save for future goals. By understanding your income and expenses, prioritizing your needs, and tracking your spending, you can create a budget that works for you. Remember to adapt your budget as needed and stay committed to your financial goals for lasting success.
Sources and further reading
- CFPB: Your Money, Your Goals toolkit
- CFPB: An essential guide to building an emergency fund
- CFPB: Consumer tools

Peter Igunnu
Peter Igunnu is the founder and editor of GuideToYourMoney. He holds a PhD in Banking and Finance, with research covering financial inclusion, green finance and AI in finance. He writes to make money decisions simpler for everyday readers.