Our content is for education only and is not personal financial advice. Some links may earn us a commission at no cost to you, which never affects our recommendations.
Key takeaways
- Dollar-cost averaging involves regular investments over time.
- It helps mitigate the impact of market volatility.
- This strategy is beneficial for long-term investors.
- It can lead to accumulating more shares at lower average costs.
Introduction to Dollar-Cost Averaging
Investing in the stock market can often feel overwhelming, especially when prices fluctuate significantly. One strategy that can help reduce the stress of timing the market is known as dollar-cost averaging. This method allows investors to build their portfolios gradually and systematically, rather than trying to predict the perfect moment to buy. In this article, we’ll delve into what dollar-cost averaging is, how it works, and its benefits for everyday investors.
Dollar-cost averaging involves investing a fixed amount of money into a particular investment at regular intervals, regardless of the asset’s price. This means you buy more shares when prices are low and fewer shares when prices are high. Over time, this strategy can lead to a lower average cost per share, which can enhance your long-term investment returns. It is particularly useful for those who are just starting their investment journey or for those looking to build their wealth steadily.
While dollar-cost averaging is not a foolproof strategy that guarantees profits, it helps to mitigate the risks associated with market volatility. By committing to invest regularly, you can avoid the pitfalls of emotional investing, where decisions are often based on fear or greed. Instead, you stick to a plan that emphasizes consistency and discipline.
How Dollar-Cost Averaging Works
To fully grasp the concept of dollar-cost averaging, it’s beneficial to understand how the process unfolds over time. Let’s break it down into several steps:
- Select a Fixed Investment Amount: Determine a specific amount of money you will invest regularly. This could be monthly, quarterly, or bi-weekly, depending on your financial situation.
- Choose Your Investment: Identify the asset or assets you want to invest in. This could be stocks, mutual funds, or exchange-traded funds (ETFs). Each option has its own benefits and risks, which you should consider carefully.
- Invest Regularly: Commit to investing that fixed amount at the chosen intervals. Stick to your schedule regardless of market conditions. This consistency is key to dollar-cost averaging.
- Monitor Your Investments: While dollar-cost averaging requires a long-term mindset, it’s still important to keep an eye on your investments and adjust your strategy if necessary. Market conditions or personal financial situations may change.
Let’s illustrate this with a simple example:
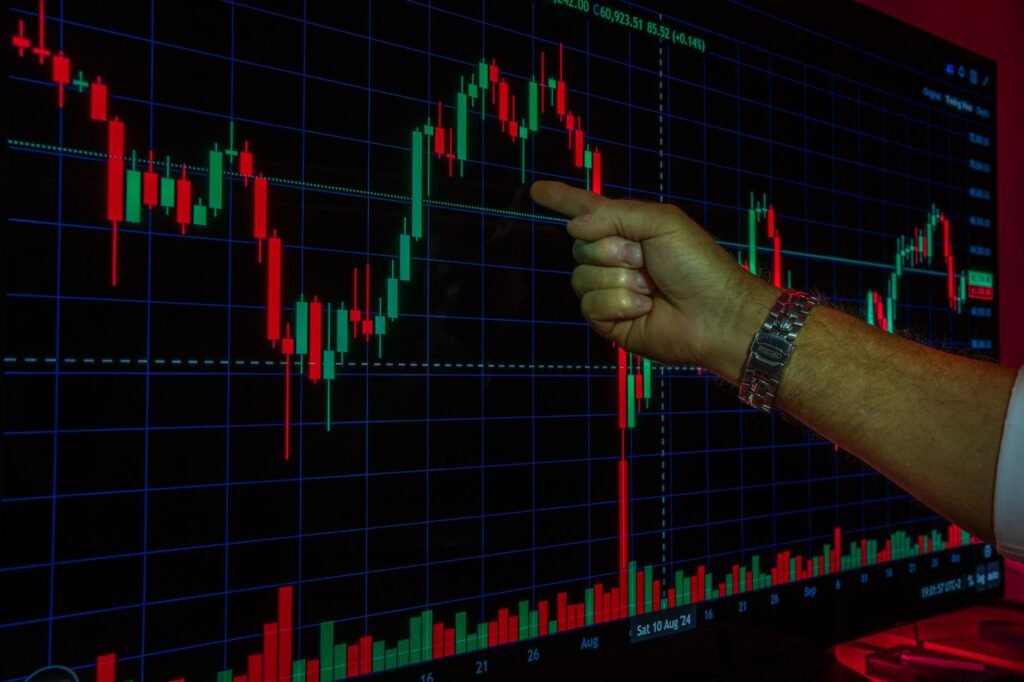
If you decide to invest $100 every month in a particular stock, you will buy more shares when the price is low and fewer shares when the price is high. Over a year, the price of the stock may fluctuate significantly, but your consistent investment means you will average out the cost of your shares.
The Benefits of Dollar-Cost Averaging
Dollar-cost averaging offers several advantages, making it a popular choice among both novice and experienced investors. Here are some key benefits:
- Reduces Emotional Investing: By sticking to a regular investment schedule, you minimize the risk of making impulsive decisions based on market fluctuations.
- Simplifies Investment Decisions: You don’t need to worry about timing the market. This makes investing easier, especially for those who may not have the time or expertise to analyze market trends.
- Potential for Lower Average Costs: As mentioned, buying more shares when prices are low can lower your overall cost per share, which may lead to higher returns in the long run.
- Encourages Discipline: Consistent investing requires discipline and commitment, which can foster better financial habits over time.
- Suitable for All Market Conditions: Whether the market is rising or falling, dollar-cost averaging can be applied effectively, allowing you to adapt to various economic environments.
When to Use Dollar-Cost Averaging
While dollar-cost averaging is a sound investment strategy, it isn’t necessarily suitable for everyone or for every situation. Here are some scenarios where this approach makes sense:
- Long-Term Investing: If you are investing for retirement or other long-term goals, dollar-cost averaging can help you build wealth over time without stressing about short-term market volatility.
- New Investors: If you’re just starting with investing, using this strategy can help you ease into the market and build confidence in your investment decisions.
- Volatile Markets: In uncertain economic conditions, dollar-cost averaging can provide a buffer against market swings, allowing you to continue investing without fear of losing money.
- Regular Income: If you have a steady income, dollar-cost averaging allows you to invest a portion of your earnings consistently, further enhancing your financial growth.
However, it’s essential to remember that dollar-cost averaging does not guarantee a profit or protect against losses in declining markets. It’s always wise to evaluate your financial situation and goals before deciding on an investment strategy.
Comparing Dollar-Cost Averaging with Lump-Sum Investing
Another common investment approach is lump-sum investing, where a large sum of money is invested all at once. Each method has its advantages and disadvantages. Below is a comparison to help you understand the differences:
| Feature | Dollar-Cost Averaging | Lump-Sum Investing |
|---|---|---|
| Investment Timing | Regular intervals | Single investment at once |
| Risk Exposure | Lower risk during volatility | Higher potential for short-term loss |
| Market Conditions | Works well in fluctuating markets | May benefit in rising markets |
| Emotional Impact | Reduces emotional decision-making | Can lead to stress and anxiety |
| Cost Basis | Average cost per share | Single cost basis |
In general, for investors who are concerned about market volatility and who prefer a more cautious approach, dollar-cost averaging may be more appealing. On the other hand, if an investor has a significant amount of cash available and believes the market is favorable, lump-sum investing might yield better returns over time.
How to Get Started with Dollar-Cost Averaging
If you are interested in implementing dollar-cost averaging into your investment strategy, here are some practical steps to consider:
- Evaluate Your Financial Goals: Define what you are investing for, be it retirement, a home purchase, or education funds. Knowing your goals will help you choose the right investment vehicle.
- Set a Regular Investment Schedule: Decide how much you can comfortably invest on a regular basis. This could be monthly or any other interval that suits your financial situation.
- Open an Investment Account: Choose a brokerage account or a retirement account like an IRA, where you can set up automatic contributions to make dollar-cost averaging easier.
- Choose Your Investments: Research and select the assets you want to invest in, keeping in mind your risk tolerance and investment horizon.
- Automate Your Contributions: Most investment platforms allow you to automate your contributions, ensuring that you stick to your dollar-cost averaging plan without having to think about it.
These steps can help you establish a disciplined approach to investing, making it easier to build wealth over time.
Common Misconceptions About Dollar-Cost Averaging
Myth 1: Dollar-Cost Averaging Guarantees Profits
One of the primary misconceptions about dollar-cost averaging (DCA) is that it guarantees profits over time. While DCA can help mitigate the impact of market volatility, it does not eliminate the risk of losing money. The strategy involves investing a fixed amount regularly, regardless of market conditions, which can lead to purchasing more shares when prices are low and fewer shares when prices are high. However, if the overall market trend is downward, even a consistent investment strategy may yield losses.
Investors must understand that market performance is unpredictable. While DCA can reduce the emotional stress of investing, it does not assure favorable outcomes. Instead, it is a strategy designed to promote disciplined investing and reduce the average cost of shares over time.
Myth 2: Dollar-Cost Averaging is Only for New Investors
Another common misconception is that dollar-cost averaging is exclusively beneficial for novice investors. In reality, this strategy can be advantageous for investors at all experience levels. Seasoned investors may use DCA to enter positions in volatile markets or to invest excess cash without attempting to time the market. This approach reduces the emotional decision-making that can lead to poor investment choices.
Moreover, DCA allows investors to gradually build positions in their desired assets, which can be particularly helpful in situations where they are uncertain about the timing of their investments. By consistently investing a set amount, even experienced investors can avoid the pitfalls of trying to predict market movements.
Myth 3: Dollar-Cost Averaging is Only Effective in Bull Markets
Many investors believe that DCA is only effective during bull markets when asset prices are rising. This is far from the truth. DCA can be particularly useful during bear markets as well, as it allows investors to buy at lower prices. By investing a consistent amount, investors can take advantage of market downturns and potentially benefit from the recovery when the market rebounds.
In fact, during bear markets, DCA can lead to a lower average cost per share, which can enhance long-term returns when the market eventually recovers. Investors should not shy away from using DCA in uncertain market conditions; rather, they should view it as a way to pursue disciplined investing through market cycles.
Integrating Dollar-Cost Averaging into a Comprehensive Investment Strategy
Complementing DCA with Other Investment Strategies
While dollar-cost averaging is a powerful strategy on its own, it can be even more effective when combined with other investment strategies. One approach is to use DCA in conjunction with value investing, where investors look for undervalued assets and use DCA to accumulate shares over time. This can help build a position in quality investments while minimizing the risk associated with market timing.
Additionally, asset allocation is crucial when integrating DCA into an investment strategy. Investors should consider diversifying their portfolios across various asset classes, such as stocks, bonds, and real estate, while using DCA to maintain consistent contributions to each category. This diversification can help in risk management and achieve more stable returns over time.
Setting Up a DCA Plan
Establishing a dollar-cost averaging plan requires careful planning and discipline. Here are some steps to consider when setting up a DCA strategy:
- Determine Your Investment Amount: Decide how much money you can afford to invest regularly without impacting your everyday finances.
- Select Your Investment Frequency: Choose a consistent interval for your investments, such as weekly, bi-weekly, or monthly.
- Choose Your Investment Vehicle: Identify the assets or funds in which you wish to invest, such as individual stocks, index funds, or mutual funds.
- Automate Your Investments: Set up automatic contributions through your brokerage or retirement account to ensure consistency and avoid emotional decision-making.
Monitoring Your DCA Strategy
Although dollar-cost averaging is a long-term strategy, it is essential to periodically review and adjust your plan. Monitoring your investments can help you determine if adjustments are necessary based on changes in your financial situation or market conditions. Here are some factors to consider during your reviews:
- Performance Evaluation: Assess how your investments are performing compared to your expectations and financial goals.
- Rebalancing Your Portfolio: Ensure that your asset allocation remains aligned with your investment strategy and risk tolerance.
- Adjusting Contribution Amounts: If your financial situation changes, consider increasing or decreasing your DCA contributions accordingly.
The Psychological Benefits of Dollar-Cost Averaging
Reducing Investment Anxiety
Investing can be an emotional rollercoaster, particularly during periods of market volatility. Dollar-cost averaging provides a structured approach that can help alleviate anxiety associated with investing. By committing to a regular investment schedule, investors can sidestep the emotional ups and downs that often accompany market fluctuations.
Furthermore, DCA encourages a focus on long-term goals rather than short-term market movements. This mindset shift can help investors feel more secure in their decisions, knowing they are consistently contributing to their investment over time.
Promoting Financial Discipline
Dollar-cost averaging inherently promotes financial discipline, as it requires investors to commit to a consistent investment strategy. This discipline can extend beyond investing and encourage better overall financial habits, such as budgeting and saving. By integrating DCA into their financial routine, investors may find themselves more mindful of their spending and saving practices.
Additionally, the act of regularly investing helps reinforce the habit of setting aside money for future needs, fostering a sense of financial responsibility and awareness.
Building Confidence in Investment Decisions
For many investors, making investment decisions can be daunting, especially in turbulent market conditions. Dollar-cost averaging can help build confidence by removing the pressure to time the market effectively. As investors witness the gradual accumulation of their investments, they may feel more comfortable with their investment choices.
Moreover, the consistent approach of DCA can instill a sense of control over one’s financial future. This empowerment can lead to a more positive outlook on investing and encourage individuals to be more proactive in managing their portfolios.
Be cautious of common mistakes when using dollar-cost averaging.
- Failing to adjust your investment amount as your financial situation changes
- Investing in high-fee funds that can erode returns over time
- Neglecting to review your portfolio regularly for performance
- Becoming overly aggressive in down markets and deviating from your strategy
Frequently Asked Questions
1. Can dollar-cost averaging guarantee profits?
No, dollar-cost averaging does not guarantee profits. While it can reduce the impact of market volatility, it does not protect against losses during a down market.
2. Is dollar-cost averaging suitable for all types of investments?
Dollar-cost averaging is most effective with investments that are subject to price fluctuations, such as stocks or mutual funds. It may not be as beneficial for fixed-income investments.
3. How often should I invest if I choose dollar-cost averaging?
The frequency of investments depends on your financial situation. Monthly contributions are common, but you can choose any interval that works for you.
4. What types of investments are best for dollar-cost averaging?
Common options include index funds, ETFs, and mutual funds, as they provide diversification and have lower risks compared to individual stocks.
The Bottom Line
Dollar-cost averaging is a practical investment strategy that allows individuals to invest regularly and mitigate market volatility. By committing to a fixed investment amount over time, you can potentially reduce your average cost per share and build wealth gradually. While it is not a foolproof method for guaranteeing profits, it encourages disciplined investing and can be particularly beneficial for those new to investing or those looking to manage risk effectively. If you want to learn more about investing basics, check out our guide on How to Start Investing With Little Money or explore the differences between Index Funds vs. ETFs.
Sources and further reading
- Investor.gov (SEC): Introduction to investing
- Investor.gov: Asset allocation
- Investor.gov: Assessing your risk tolerance

Peter Igunnu
Peter Igunnu is the founder and editor of GuideToYourMoney. He holds a PhD in Banking and Finance, with research covering financial inclusion, green finance and AI in finance. He writes to make money decisions simpler for everyday readers.